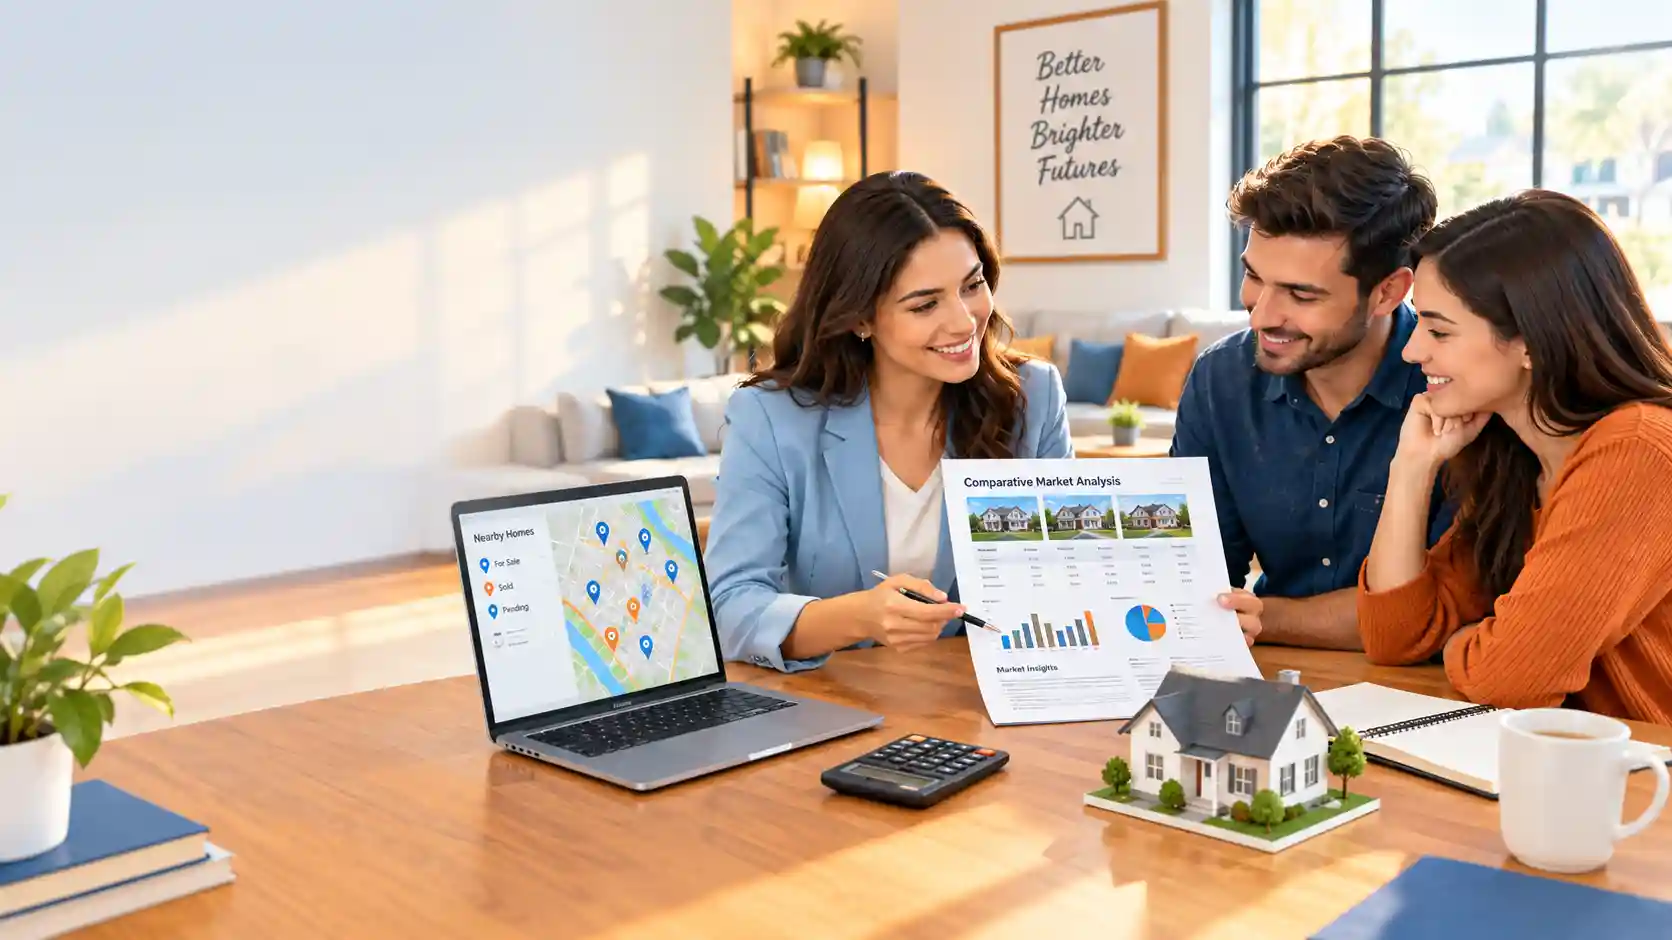
Maybe your agent just said, “Let’s run a CMA.” You nodded, but you had no idea what it meant. You are not alone. Many home buyers and sellers search for the CMA real estate meaning every day. CMA stands for Comparative Market Analysis. It is a report that helps set a fair price for a home by looking at similar homes that sold nearby.
Think of it as a price check for a house. You would not buy a car without checking what similar cars cost. Homes work the same way. In this guide, you will learn what a CMA is, what goes inside it, and how agents build one. You will also see how it differs from an appraisal, how much it costs, and how to read one with confidence.
Quick Answer:
In real estate, CMA means Comparative Market Analysis. It is a report made by a real estate agent or broker. It compares a home to similar homes (“comps”) that recently sold, are for sale, or did not sell. The goal is to find a smart list price for a seller or a fair offer price for a buyer.Some agents say “Competitive Market Analysis” instead. The meaning is the same. Both names describe the same job: comparing your home to the market around it.A CMA is not a guess. It is also not a final, official value. It is an informed estimate built from real sales data. That makes it one of the most useful tools in a home sale.
Why a CMA Matters for Sellers and Buyers
Price is the biggest decision in any home sale. If a seller sets the price too high, buyers may skip the home. It can then sit on the market for weeks or months. Long time on the market can make buyers wonder if something is wrong with the house. If a seller sets the price too low, they may lose thousands of dollars.
A CMA helps sellers find the sweet spot. It shows what buyers in the area have actually paid. That is much better than picking a number because a neighbor “got a great price” last year.
Buyers use CMAs too. Say you find a home you love, and the price feels high. A CMA can show whether similar homes sold for less. Then you can make an offer with real facts behind it. Many buyers feel calmer when they have numbers to lean on.
Here is a simple example. Imagine a three-bedroom home listed at $350,000. A CMA finds three similar homes nearby that sold for $325,000, $332,000, and $338,000 in the last few months. A buyer might reasonably offer less than the asking price. A seller who sees the same report might lower the price to attract more interest.
What Is Included in a CMA Report
A good CMA is more than a single number. It is a small package of facts and notes. While every agent’s report looks a little different, most include the same key parts.
First, there is a description of the home being studied. This covers the size, age, number of bedrooms and bathrooms, lot size, and condition. Next comes the list of comparable homes. Each one gets its own details, such as sale price, sale date, and features.
Agents also look at homes in three groups. Sold homes show what buyers actually paid. Active listings show your competition right now. Expired or withdrawn listings show homes that did not sell, which often means they were priced too high.
The table below shows the main parts of a CMA and why each one matters.
| CMA Part | What It Shows | Why It Matters |
|---|---|---|
| Subject property details | Size, age, rooms, condition, lot | Sets the starting point for comparison |
| Sold comps | Homes that recently closed | Shows real prices buyers paid |
| Active listings | Homes for sale right now | Shows current competition |
| Expired or pending listings | Homes that did not sell or are under contract | Shows what the market will not accept |
| Price per square foot | Cost compared to home size | Gives a quick way to compare homes |
| Days on market | How fast similar homes sold | Shows how hot or slow the market is |
| Suggested price range | The agent’s estimate | Guides the list price or offer |
How Agents Choose Comparable Homes
Picking the right comps is the heart of a CMA. If the comps are wrong, the price will be wrong too. So agents follow a few common rules of thumb.
Location comes first. Agents like to use homes in the same neighborhood, and often within about a half mile to one mile. In busy cities, the range may be smaller. In country areas, it may be much larger because homes are far apart.
Timing comes next. Most agents prefer homes that sold in the last three to six months. Prices can change fast, so older sales may not tell the true story. In a slow area with few sales, an agent may look back further.
Then comes the home itself. A good comp is close in size, often within about 10 to 20 percent of the subject home’s square footage. It should also have a similar age, style, bedroom count, and lot size. A tiny starter home is a poor match for a large family house, even if they sit on the same street.
Finally, condition matters. A home with a new kitchen and a fresh roof will usually sell for more than a similar home that needs work. Agents note these differences carefully.
How a CMA Is Done, Step by Step
Many people think a CMA is a machine-made number. In truth, a skilled agent puts real thought into it. Here is how the process usually goes.
The agent starts by gathering facts about the home. Often this includes a visit, where the agent walks through the rooms and takes notes. They look at updates, damage, and special features like a pool or finished basement.
Next, the agent searches the Multiple Listing Service, often called the MLS. This is a shared database used by real estate professionals. It holds sales data, photos, and listing details. Agents may also check public records for extra facts, like tax information and lot size.
After that, the agent picks the best comps. Most reports use around three to six strong ones. Using too few can give a shaky result. Using too many weak ones can water down the answer.
Then comes the step that takes real skill: making adjustments. No two homes are exactly alike, so the agent adds or subtracts dollars to account for the differences. If a comp has a garage and the subject home does not, the agent lowers the comp’s price a bit to make it fair. If the subject home has a newer roof, the agent adjusts the other way.
Last, the agent studies the results and suggests a price range. Good agents also explain their reasoning. They should be able to tell you why each comp was picked and how the final number was reached.
A Simple Example of How Adjustments Work
Adjustments can sound confusing, so let’s walk through a made-up example. The numbers below are only for teaching. Real adjustment amounts depend on your local market.
Say you want to sell a three-bedroom home with no garage. The agent finds a similar home that sold for $300,000. That home had a one-car garage, which the agent estimates adds about $10,000 in value in that area. It also had an updated bathroom worth about $5,000 more.
| Feature | Comp Home | Your Home | Adjustment to Comp |
|---|---|---|---|
| Sale price | $300,000 | n/a | Starting point |
| Garage | One-car garage | None | −$10,000 |
| Bathroom | Updated | Older | −$5,000 |
| Bedrooms | 3 | 3 | $0 |
| Adjusted value | $285,000 | n/a | Result |
After adjusting, the comp suggests your home may be worth around $285,000. The agent repeats this with the other comps. If they land near the same number, the agent can feel more sure about the final price range.
CMA vs. Appraisal: What Is the Difference?
This is one of the most common questions people ask. A CMA and an appraisal sound alike, but they are not the same thing.
An appraisal is an official value opinion from a licensed or certified appraiser. Lenders usually require one before they approve a mortgage. The appraiser is meant to be neutral, and the report follows strict rules.
A CMA is made by a real estate agent. It is meant to help with pricing and strategy. It is less formal, and it does not carry the same weight with a bank.
There is one more tool worth knowing, called a Broker Price Opinion, or BPO. Banks sometimes use it, especially for homes that are in foreclosure or need a quick value check. It is similar to a CMA, but it is usually done for a lender rather than for a seller.
| Feature | CMA | Appraisal | Broker Price Opinion |
|---|---|---|---|
| Who does it | Real estate agent or broker | Licensed or certified appraiser | Real estate agent or broker |
| Main purpose | Set a list price or offer price | Support a mortgage loan | Give a lender a quick value estimate |
| How official is it | Informal | Formal and regulated | Semi-formal |
| Typical cost | Often free from an agent | Usually a few hundred dollars | Often paid by a lender |
| Accepted by lenders for a loan | Usually not | Yes | Sometimes, for special cases |
The short version is simple. A CMA helps you decide on a price. An appraisal helps a bank decide whether to lend money.
How Much Does a CMA Cost?
For most people, a CMA costs nothing. Agents commonly offer them for free, because they hope to earn your business when you list or buy a home. It is a way for the agent to show their skills before you sign anything.
That said, prices can vary. Some agents or brokerages may charge a fee for a very detailed report, especially if you are not planning to hire them. If someone asks you to pay, feel free to ask what is included first.
An appraisal, by comparison, is a paid service. Costs often run in the hundreds of dollars and depend on the home and location. So a free CMA is a great first step before you spend money on anything else.
Online home value tools also exist, and many are free. These can be handy for a rough idea. But they often miss details like a fresh remodel, bad foundation, or a busy road. A CMA from a local agent usually goes deeper, because the agent knows the neighborhood.
Common Mistakes People Make With CMAs
Even a helpful tool can lead people astray if it is used the wrong way. Here are some mistakes to watch out for.
One big mistake is treating the CMA as a promise. A CMA suggests a likely price range, but the real price is whatever a buyer will pay. Market changes, buyer moods, and even the season can shift results.
Another mistake is picking an agent just because they suggest the highest price. Some agents may inflate the number to win your listing. Then the home sits, and the price drops later. A fair, well-backed number is worth more than a flashy one. Ask the agent to show you their comps, and see if they truly match your home.
Sellers also tend to fall in love with their own homes. It is natural. You may remember the birthdays, the garden, and the paint you picked yourself. But buyers pay for the home’s features and condition, not your memories. A good CMA can feel like a reality check, and that is okay.
Some people compare their home to the wrong homes. A house across town, or one that sold two years ago, may not be a fair match. Old data can be very misleading, especially when prices have moved a lot.
Finally, some folks forget about condition. Two homes can look alike on paper, yet one may need a new roof while the other is move-in ready. If a CMA ignores those details, its result may be off.
Real-Life Example
Let’s look at how a CMA plays out in a few everyday situations.
Maria wants to sell her family home. She calls two local agents. Each agent visits and creates a CMA. One suggests $410,000, and the other suggests $385,000. Maria asks both agents to explain their comps. The first agent used a newly built home that was much larger than Maria’s. The second agent used homes that were closer to hers in size and age. Maria trusts the second report more and lists at a price that draws several showings in the first week.
Now think about James, a first-time buyer. He finds a townhouse listed at $250,000. He asks his agent for a CMA. It shows that three similar townhouses sold for $235,000 to $242,000 in the past four months. James offers $240,000. The seller counters, and they settle at $243,000. James feels good because he knows his price is backed by facts.
Here is a third case. A couple wants to refinance and asks a real estate friend for a quick CMA. The friend gives them a rough number. But when they apply, the lender orders a formal appraisal. This is normal. The CMA gave them a helpful guess, while the appraisal met the bank’s rules.
Current Trends: How CMAs Are Changing
Technology has changed how CMAs are made. Agents now use software that pulls in sales data in minutes. Many tools can build a clean, colorful report with maps, charts, and photos. Some even let agents share the report through a link or a mobile app.
Automated valuation models, often called AVMs, are also common. These computer tools estimate a home’s value using data and formulas. They can be fast and handy, but they cannot see the inside of a home. That is why many experts see them as a starting point rather than the final word.
Still, the human touch matters. A local agent knows if a new school is opening, if a big employer is moving in, or if a noisy road makes buyers nervous. Software cannot always catch those things. The best CMAs mix good data with local know-how.
It is also worth saying that markets change. In a fast market, prices can rise quickly, and older sales may fall behind. In a slow market, homes may sit longer, and prices may soften. A fresh CMA is more useful than an old one, so ask for an update if the market shifts.
Tips for Getting the Most From a CMA
A CMA is only as helpful as the way you use it. Here are some practical ways to get real value from one.
Ask to see the comps. Look at the photos, sizes, and sale dates. Do they seem like fair matches to you? If something feels off, ask why the agent picked it.
Be honest about your home’s flaws. If your roof is old or your kitchen is dated, tell your agent. It is better to plan for these issues now than to be surprised by a low offer later.
Compare more than one opinion. If you are selling, you might ask two or three agents for a CMA. Look for patterns. If they all land close together, that is a good sign. If one is far away from the rest, ask why.
Think about strategy, not just the number. A CMA can help you decide whether to price a bit lower to start a bidding war, or price higher and leave room to negotiate. Your agent’s advice on timing and marketing matters too.
Finally, keep your eyes on the market. If your home has been listed for a few weeks with little interest, ask for an updated CMA. The data may show that similar homes are selling for less, and a small price change could bring in buyers.
FAQs
What does CMA stand for in real estate?
CMA stands for Comparative Market Analysis. Some agents call it a Competitive Market Analysis. Either way, it is a report that compares a home to similar homes nearby to help set a fair price.
Is a CMA the same as an appraisal?
No. A CMA is made by a real estate agent to help with pricing. An appraisal is made by a licensed or certified appraiser, and lenders usually require it for a mortgage. Appraisals are more formal and follow stricter rules.
How accurate is a CMA?
A CMA can be quite helpful when it uses good comps and fresh sales data. But it is still an estimate, not a guarantee. The final price depends on what buyers are willing to pay at that time.
Can I get a CMA for free?
Yes, in most cases. Many agents give free CMAs to people who are thinking about buying or selling. Some may charge for a very detailed report, so it is smart to ask before you agree to anything.
How long does a CMA take?
It varies, but many agents can finish one in a day or two. If the agent needs to tour the home first, it may take a little longer. A CMA for a unique home with few comps can take more time.
How often should a CMA be updated?
It depends on the market. In fast-moving markets, an update every few weeks may make sense, especially if your home has not sold. In steady markets, an update every few months can be enough.
Conclusion
Now you know the CMA real estate meaning. CMA stands for Comparative Market Analysis, and it is one of the smartest tools for pricing a home. It uses real sales, current listings, and careful adjustments to point toward a fair price. It is not an appraisal, and it is not a promise. But it gives buyers and sellers solid facts to lean on.
If you plan to sell, ask an agent for a CMA and look closely at the comps. If you plan to buy, use one to back up your offer. Either way, ask questions and make sure the report makes sense to you. A good agent will be happy to explain every step. The more you understand your local market, the more confident your next move will be.
Hi, I’m Mishi, a content writer and researcher specializing in meanings, interpretations, and informative explanations. With 2 years of experience creating clear, engaging, and SEO-friendly content, I help readers understand the meanings behind words, phrases, names, symbols, numbers, and everyday expressions.
My goal is to provide simple, accurate, and easy-to-understand information that answers readers’ questions while making every topic interesting and useful.